LICENSED IN FL · IL · MN  ·  INDEPENDENT AGENCY  ·  50+ CARRIERS
J&J Elite Insurance Group logo
J&J Elite Insurance Group
YOUR COVERAGE. OUR PRIORITY.
J&J Elite Insurance GroupYOUR COVERAGE. OUR PRIORITY.
AutoHomeCommercialFloodRentersCondoBoatFAQAboutContactCall (407) 255-8220
AutoHomeCommercialFloodRentersCondoBoatFAQAboutContact
FLOOD INSURANCE

Flood is never in your homeowners policy

NFIP or private market, with or without an elevation certificate. We quote both and show you the difference in writing.

50+
CARRIERS
2 min
TO A REAL QUOTE
EN · ES
WE SPEAK BOTH
Ava
AvaOnline now · replies in seconds
EN · ES
Hi! I can put together a flood quote for you right here. What's the address of the property you want to cover?
4700 Millenia Blvd, Orlando, FL 32839
About when was it built?
Type your answer
SEND
A few quick questions · no spam · a licensed agent reviews every quote
Ava
AvaOnline now · EN · ES

I can put together a flood quote right here — a few quick questions, about two minutes.

Chat with Ava
Opens full screen · no app to install

What a flood policy actually covers

Plain English, no jargon. Tap any coverage in the chat and Ava explains it while you answer.

Building coverage

The structure itself: foundation, walls, electrical, plumbing, built-in appliances.

Contents coverage

Your belongings, bought separately from the building. Most flood claims need both.

Private market

Often higher limits and faster binding than NFIP, and sometimes cheaper. Worth comparing every year.

Zone review

Zone X does not mean no risk — a third of flood claims come from outside high-risk zones.

Explore what flood coverage actually pays

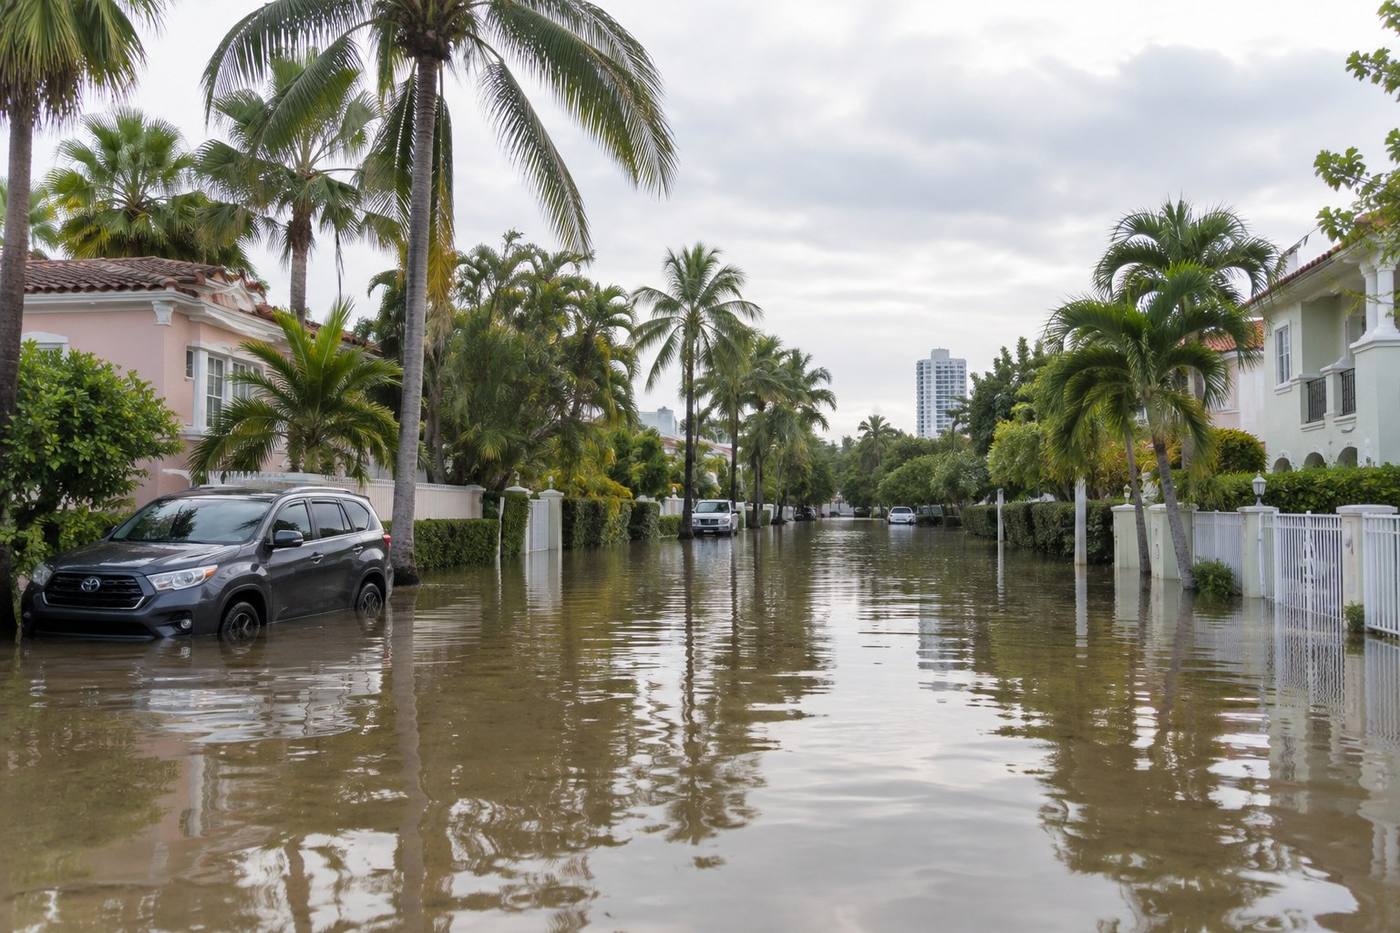
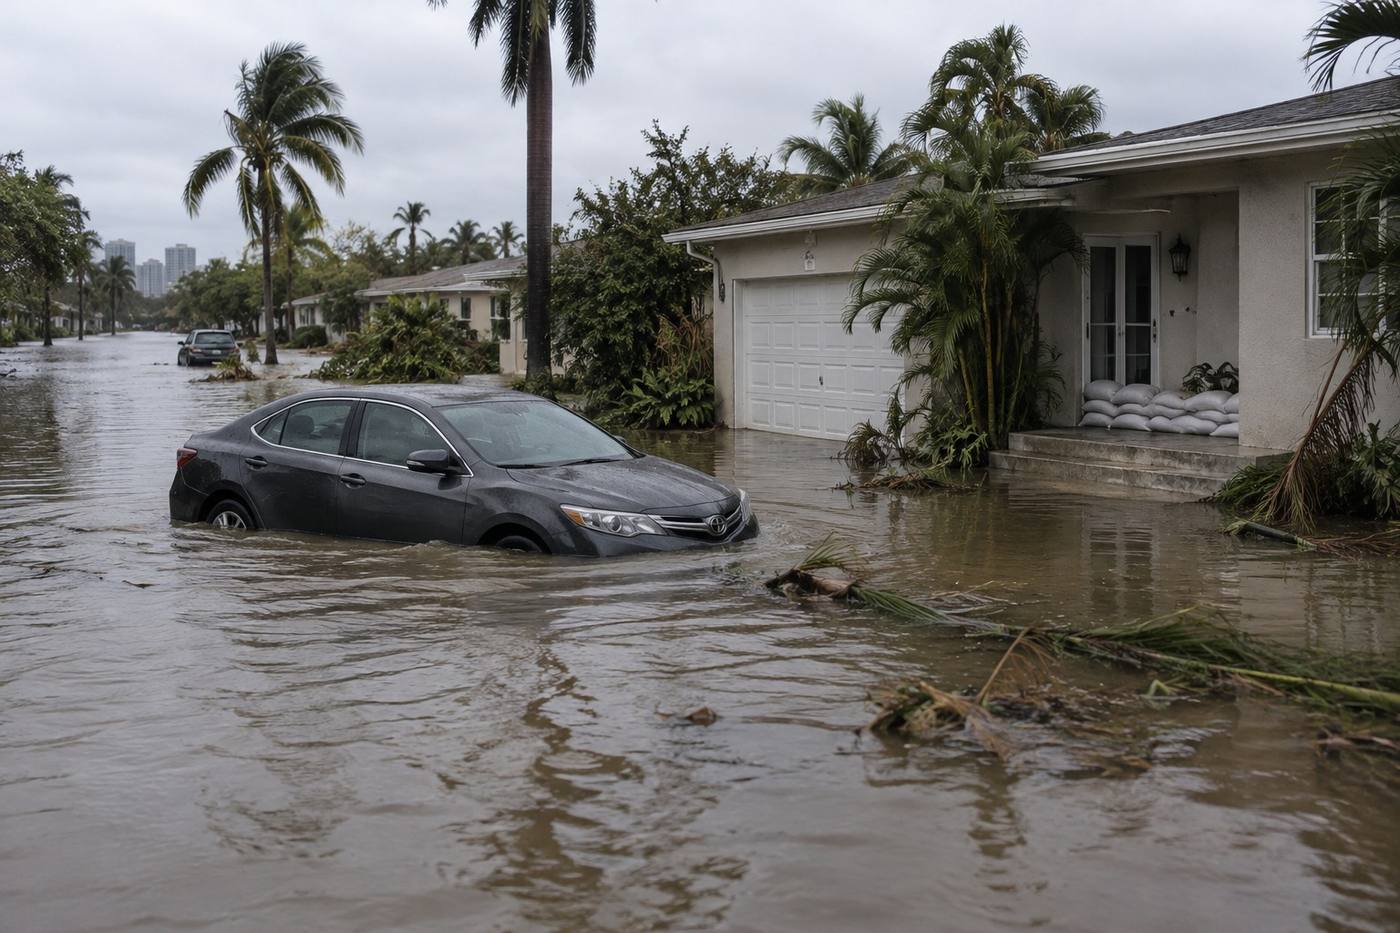
Flood is never part of a homeowners policy. Click a hotspot to see what a flood policy does and does not answer.

FLOOD INSURANCE MAP

Building Coverage

Risk factor

Rising water damages the structure itself: framing, drywall, flooring, electrical, and the air conditioning equipment.

Solution

Building coverage repairs the structure. NFIP caps it at 250,000 dollars; private carriers often go higher, which matters on a newer or larger home.

Contents Coverage

Risk factor

Furniture, electronics and everything stored at ground level are usually the first total loss in a flood.

Solution

Contents coverage is separate from building coverage and has its own limit — 100,000 dollars under NFIP. Buying one without the other is the classic mistake.

Vehicles Are Not Covered

Risk factor

A flooded car is one of the most common losses in a storm, and a flood policy does not pay for it.

Solution

A flooded vehicle is a comprehensive auto claim. If you carry liability only, nobody pays for that car — which is why we check both policies together.

The 30-Day Wait

Risk factor

NFIP policies normally take effect 30 days after purchase, so the week a storm is named is far too late to buy.

Solution

Private flood often binds much faster. Either way, the right time to place flood coverage is a calm week in the off-season.

Zone & Elevation

Risk factor

About a third of flood claims happen outside high-risk zones, where owners assumed they did not need a policy.

Solution

In Zone X the premium is a fraction of high-risk pricing. An elevation certificate can move the number by hundreds — send it if you have one.

WHAT AVA WILL ASK YOU

The same questions a licensed agent would ask on the phone — in the order that gets you an accurate number instead of a teaser rate.

  • What's the address of the property you want to cover?
  • About when was it built?
  • Approximately how many square feet?
  • Do you know your flood zone?
  • Do you have an elevation certificate?
  • How is this property used?

…and a few more. Average time: under two minutes.

AND THEN?
1

It lands with a licensed agent

Not a lead broker, not a call center. Your answers go straight into our agency system.

2

We shop it across 50+ carriers

Including the ones that never show up on comparison sites.

3

You get real numbers, same day

By email or text, whichever you picked. No pressure, no endless calls.

Prefer a human right away? Call (407) 255-8220.

Ready for a real flood quote?

Ava starts it. A licensed agent finishes it.

J&J Elite Insurance Group

Independent agency licensed in FL · IL · MN. We compare 50+ carriers and place the policy that actually fits — no call center, no quote farm.

Licensed agent 2-20 · Florida
Talk to us
(407) 255-8220 lvelez@jjeliteinsurancegroup.com

4700 Millenia Blvd, Suite 500
Orlando, FL 32839

Mon–Fri 9 AM–5 PM

Start my quote
Quotes are subject to carrier underwriting approval and final premium may differ. J&J Elite Insurance Group is an independent insurance agency, not an insurer.
© 2026 J&J Elite Insurance Group · Licensed in FL · IL · MNPrivacy · Terms · Powered by Arlo